The most common mistake new UAE expats make on points and miles is treating one mile as equivalent to one mile. They are not. A Skywards Mile, an Etihad Guest Mile, and 1 Smiles point earned on the same AED of spend can differ in value by a factor of three or more — and earning the wrong one for the trips you actually take is worse than earning fewer of the right one.
This is the entry-level orientation. For the value we put on each UAE programme’s currency, see our AED valuations page.
This guide is part of the DubaiPoints Expat Starter track.
The two airline currencies that matter
In the UAE, two airline programmes do most of the work:
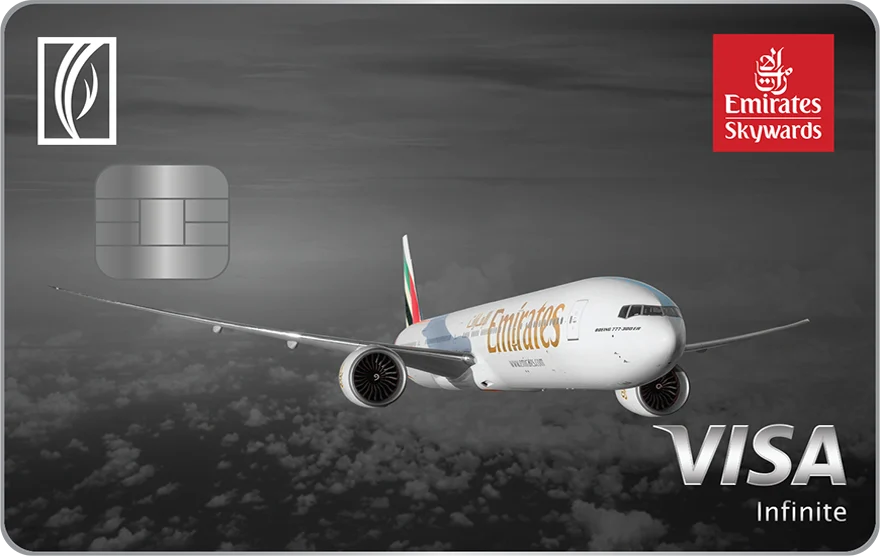
Emirates Skywards. Earned directly on a small set of UAE-issued co-brand credit cards (the Emirates NBD Skywards Infinite and Skywards Signature among them) and through Emirates and flydubai paid flights. Best used on Emirates premium-cabin redemptions out of DXB. Approximate indicative value: 2.0–2.5 fils per Mile, with peaks in business-class redemption availability and troughs on partner-airline awards.
Etihad Guest. Earned directly on a smaller set of co-brand cards (the FAB Etihad Guest Infinite and Emirates NBD’s Etihad Guest Inspire and Elevate among them) and through Etihad and partner paid flights. Best used on Etihad metal out of AUH. Approximate indicative value: 1.8–2.2 fils per Mile.
The headline number to take away: a Mile in either programme is worth roughly two fils — which means an AED 1,000 month of spend on a 2× earning card buys you an AED 40 redemption value if used well, less if not.
Bank-proprietary points
Beyond the airlines, many UAE banks run a proprietary points programme:
- FAB Rewards — generally the highest-value bank-proprietary programme, with Skywards as the strongest exit; FAB does not publish the ratio, so check the in-app rate (see the transfer-ratios guide).
- ADCB TouchPoints — most often used for statement credit. Reliable, not exciting.
- Emirates NBD Plus Points — convertible to Skywards and other partners at in-app rates; usually best taken as cashback or statement credit.
- Mashreq Reward Points — broad but shallow; convertible to cashback, flights, or shopping.
Bank-proprietary points are typically worth less per point than direct airline miles, but they have one advantage: they don’t devalue on the schedule that airline programmes do. If you are not committed to a specific airline, a bank-proprietary card with strong cashback exits often beats an airline co-brand on raw AED-equivalent value.
What “value” means in practice
When we say a Mile “redeemed at 2.4 fils”, we mean the following:
- If you redeem 100,000 Miles for a ticket whose cash price would have been AED 2,400, your Mile redeemed at 2.4 fils per Mile.
- If you redeem the same 100,000 Miles for an Emirates economy ticket priced at AED 1,200 cash, your Mile redeemed at 1.2 fils per Mile.
- If you redeem the same 100,000 Miles for a partner-airline economy ticket via the Skywards partner chart and the partner’s own price for that ticket is AED 800, your Mile redeemed at 0.8 fils per Mile.
The 2-fil baseline we publish is a deliberately conservative cost-basis floor, used to judge whether a card is worth holding; a good premium-cabin redemption can return several times that, and a poor one less. Your actual mileage will vary — that’s not a cliché, that’s literally how miles redemption works.
The redemptions worth chasing from DXB and AUH
Three sweet spots survive most programme refreshes:
- Emirates business-class to Europe on Skywards Saver awards. From 102,500 Miles plus ~AED 1,500 in surcharges for a one-way DXB-LHR, against a cash fare of AED 14,000–22,000. Fils-per-mile: roughly 12–16 (see the Skywards business-class playbook).
- Etihad business-class across the Atlantic on Guest Saver awards. From ~88,000 Miles plus AED 1,800–3,000 in surcharges for a one-way AUH-JFK, against a cash fare commonly AED 18,000–28,000. Fils-per-mile: roughly 20 (verify the current rate on Etihad’s chart; see the Etihad Guest page).
- Skywards economy on flydubai short-hauls. ~10,000–20,000 Miles for short regional flights with cash prices that hold high in weekends. Less glamorous, but the redemption rate is reliable.
The redemptions to avoid: low-availability partner-award charts (rate plummets), Skywards “Cash + Miles” hybrids (you lose value on both sides), and any programme’s own “shopping mall” or merchant gift-card redemption (rate is usually 0.5–0.8 fils per Mile).
How this should change what card you apply for
Two implications:
- If you fly Emirates regularly: the right card is one that earns Skywards Miles directly, not one that earns transferable points you could theoretically convert. The conversion rates on UAE transferable-points programmes are not strong.
- If you fly any airline / fly cash fares / fly long-haul rarely: the right card is a high-cashback or high-flat-rate-points card whose redemption is statement credit or a near-cash equivalent. Stop trying to optimise for premium-cabin redemptions you will not actually book.
What to do this week
- Look at your last 12 months of flights. Count Emirates segments and Etihad segments. If both are below 4, do not buy an airline co-brand card for the airmiles alone — you will not earn enough to redeem well.
- Decide which currency, if any, fits you: Skywards, Etihad Guest, or bank-proprietary cashback. Do not try to earn all three at once.
- Bookmark our valuations page. The value it carries for each currency is the one every card and offer recommendation on this site is priced against.